By Uchumi 360
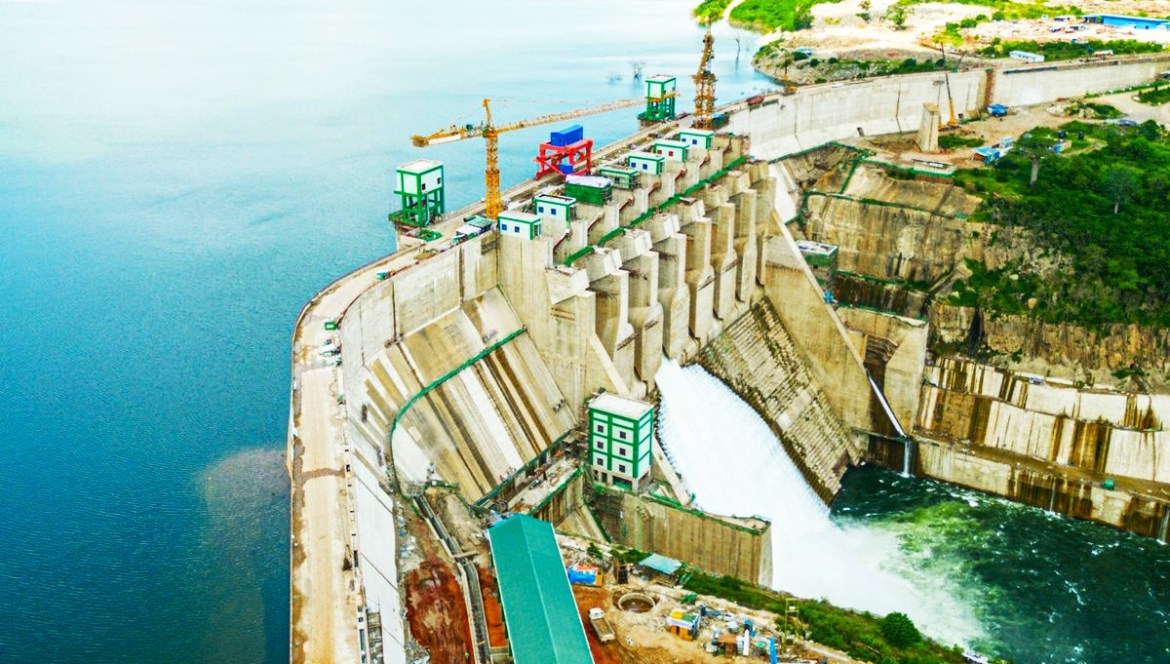
There is a temptation to treat the Julius Nyerere Hydropower Project as simply a remarkable feat of engineering.
Well, at 2,115 MW, nine generating units, and a reservoir holding roughly 32.8 billion cubic meters of water, it certainly is one.
And it almost answers the long hovering question; “How to convert the Rufiji River’s natural resources into national economic development?
That question outlived German colonial rule, British administration, independence, socialism and structural adjustment.
It has now taken physical form, and the more interesting story is what comes after.
A Century Before the Dam, the Rufiji Was Already a Development Question
German authorities investigated the Rufiji in the early 20th century, and British administrators continued surveying the river after the First World War, initially focused on irrigation and flood control rather than electricity.
By the mid-20th century, the ambition had grown considerably.
The story behind
The 1961 Food and Agriculture Organization (FAO) study envisaged roughly 200,000 hectares of irrigation in the Rufiji Basin.
Electricity later became the dominant component of that vision, but the underlying idea, using infrastructure to transform an entire economic geography, predates hydropower entirely, which is precisely why JNHPP should not be judged on megawatts alone.
Independence sharpened the political stakes without resolving the engineering question.
Julius Nyerere inherited decades of studies on the Rufiji, and through the 1960s American and Japanese institutions, including the US Bureau of Reclamation and the Tennessee Valley Authority, contributed to the thinking around the basin.
By the 1970s, Norway had become the project’s most important international partner.
Norwegian Agency for Development Cooperation (NORAD) supported feasibility studies, Norwegian engineering consultancy (Norconsult) undertook major engineering work, and Hafslund later joined the design process.
By around 1980, that work had produced a design of approximately 2,100 MW, remarkably close to the 2,115 MW Tanzania eventually built four decades later.
The technical vision, in other words, was never the missing ingredient. What Tanzania lacked was the economic and financial capacity to execute it.
Why Tanzania Waited for Decades
The project didn’t stall because earlier governments failed to grasp its potential.
It stalled because the economics genuinely weren’t favorable.
Tanzania’s economy was smaller, its electricity consumption was low, and its industrial base couldn’t obviously absorb a facility generating more than 2,000 MW.
The World Bank and other institutions questioned, reasonably, whether Tanzania could economically use a project this large.
Environmental concerns compounded the hesitation, since the proposed reservoir would fundamentally alter part of the Rufiji ecosystem, raising questions about wildlife, downstream flows and the wider Selous ecosystem.
By the 1980s, Stiegler’s Gorge was trapped between three problems at once, cost, scale mismatched to demand, and environmental consequence, and the project was effectively shelved, though never forgotten.
What eventually changed wasn’t a new engineering breakthrough.
It was Tanzania itself: the economy grew, the population expanded, urbanization accelerated, and repeated electricity shortages exposed how vulnerable the country’s generation system had become to hydrological conditions and inadequate capacity.
The argument that Tanzania couldn’t absorb a project of this scale grew steadily less convincing, illustrating a broader point about large infrastructure: a project can be uneconomic at one stage of a country’s development and transformative at another.
John Pombe Magufuli’s Decision Broke the Financing Deadlock
The decisive shift came under President John Magufuli, who committed to proceeding with the project in 2017.
The more consequential decision wasn’t reviving Stiegler’s Gorge, it was changing how Tanzania paid for it: rather than waiting on international development finance, the government chose to fund construction domestically.
In December 2018, TANESCO signed an Engineering, Procurement, and Construction Contract (EPC) contract worth approximately 6.6 trillion/-, roughly US$2.9 billion at the time, with the Egyptian joint venture of Arab Contractors and Elsewedy Electric.
Construction began in 2019 against an initial completion date of 14 June 2022, which slipped repeatedly before the project finally neared completion in 2025; Tanzania’s Controller and Auditor General reported implementation at 99.35 percent by December 2024, with government officials citing figures between 99.5 percent and 99.8 percent complete by early 2025.
The project’s renaming carried real political weight. Stiegler’s Gorge referenced the site’s colonial history; Julius Nyerere Hydropower Project tied the infrastructure explicitly to independent Tanzania’s founding development vision.
The continuity across administrations is genuinely unusual:
Nyerere’s first phase governance supplied the original development thinking, Magufuli who ruled in the fifth, supplied the political decision and financing model, and the current, sixth, government carried the project through to completion.
Few Tanzanian infrastructure projects have survived three distinct political eras intact.
The Real Project Is the Economy Around It
What does Tanzania actually do with 2,115 MW?
A dam doesn’t industrialize a country.
Electricity does, but only when it connects to productive activity.
If factories can’t connect to the grid, if transmission capacity is insufficient, if industrial electricity prices remain too high, or if Tanzania lacks enough industrial investment to absorb the new supply, the economic return on a TZS 6.55 trillion asset shrinks considerably.
The question worth asking is no longer how many megawatts Tanzania has.
It’s how much additional economic output each of those megawatts can enable.
That reframing points directly at where the electricity could do the most work: mineral processing and refining rather than raw mineral exports, manufacturing that benefits from more reliable production conditions and agro-processing that captures more value domestically than exporting raw commodities does.
Cold-chain infrastructure that reduces post-harvest losses, irrigation systems paired with more predictable water management, modern rail and logistics, and, increasingly, digital infrastructure and data centres that require dependable power above all else.
None of that happens automatically.
Energy policy and industrial policy now have to be designed together, since identifying which sectors can build a genuine competitive advantage from electricity availability, and pricing that electricity in a way that gives investors’ confidence in continued supply, is a different and harder task than building the plant itself.
The Transmission Network May Decide the Project’s Real Return
There is an uncomfortable possibility sitting underneath JNHPP’s completion: Tanzania could have solved its generation problem without fully solving its electricity-system problem.
Power still has to travel from Rufiji to consumers, which requires transmission capacity, substations and distribution infrastructure keeping pace with generation.
If the grid grows more slowly than generation capacity, Tanzania risks stranding exactly the asset it just spent a century building.
The dam cannot be evaluated apart from the grid, the grid cannot be evaluated apart from industrial demand, and industrial demand cannot be evaluated apart from investment policy, each link in that chain determines how much of JNHPP’s potential actually gets captured.
Regional Trade Could Make Tanzania an Energy Hub, but Exports Shouldn’t Be the Whole Strategy
Tanzania sits inside an increasingly interconnected East and Southern African power system, which creates a real opportunity to export surplus generation for foreign exchange and better commercial utilisation of the plant.
But there’s an important strategic distinction worth making explicit: Tanzania’s higher-value path isn’t becoming a cheap power exporter.
It’s industrialising domestically first, processing minerals, manufacturing goods, adding value to agricultural output, and exporting genuine surplus regionally on top of that.
Selling raw electricity is useful.
Using that electricity to produce goods Tanzania can sell regionally and globally is potentially far more transformative, and treating JNHPP as an economic multiplier rather than simply a power station is the difference between those two outcomes.
The Environmental Cost Is Part of the Economic Calculation
No serious assessment of JNHPP can set aside its environmental dimension.
The Rufiji Basin is one of Tanzania’s most significant ecological systems, and the dam and reservoir have raised long-standing concerns over wildlife habitat, downstream flows, fisheries, sediment movement and the broader Selous ecosystem, concerns UNESCO has separately raised regarding the site’s World Heritage implications.
The reservoir’s scale also changes Tanzania’s relationship with the river itself, shifting it from a natural system exploited for agriculture or power toward one under far greater human control, which creates new responsibilities around balancing generation against downstream ecological and agricultural needs.
The honest approach treats this as part of the same ledger as the economic case, not a separate debate: if JNHPP generates substantial economic value while its environmental impacts are genuinely monitored and mitigated, large infrastructure and environmental stewardship can coexist.
If those costs are ignored, Tanzania will simply have treated its natural capital as an invisible subsidy, which is poor economics as much as poor environmental policy.
What the Next Decade Needs to Show
The construction phase is over.
The implementation phase, the one that actually determines whether JNHPP becomes transformative, is beginning, and it will be measured across several distinct indicators rather than a single completion certificate.
How much electricity the plant actually generates relative to its installed capacity; whether the national grid can reliably evacuate that power; whether manufacturers and other productive sectors meaningfully increase their electricity consumption and whether reliable power attracts new domestic and foreign investment.
Also whether Tanzania’s mineral and agricultural exports become more processed and higher-value over time; whether genuine surplus power converts into commercially viable regional trade; whether the broader economy generates enough additional revenue and productivity to justify the public investment; and whether the Rufiji ecosystem is demonstrably being managed responsibly throughout.
Those eight indicators tell a far more meaningful story than simply reporting that nine turbines are operational.
The German surveyors, the British administrators, the FAO’s irrigation planners, Nyerere’s development vision, Norway’s engineers, and the international financiers who once doubted Tanzania could absorb a project this size were all, in different ways, asking the same underlying question the country still has to answer now that the dam exists: not whether Tanzania could build 2,115 MW, but whether it can turn that capacity into an economy worth the century it took to get there.